Showing posts with label Probability. Show all posts

Thursday, April 11, 2019

For safety, bet the average - not the trend


Protecting against loss while generating a satisfactory return is the essence of Value Investing.  As Howard S. Marks, Founder, Oaktree Capital Management, stated:

“The key to success lies in avoiding losers, not in searching for winners.”

Unfortunately, too many investors are driven by sound bites and social media posts.  The goal: find the investment rocket launching their portfolio to galactic heights.  They’re searching for “winners” among IPOs, momentum plays, fads, and who knows what else.  Investment safety is an afterthought – until it’s too late.

One way to increase the safety of my Dividend Farming practice is to look for stability and predictability in investment opportunities.  Strong dividend paying stocks have been a great way for me to do so.

Firms with long histories of dividend payments, particularly firms growing those payments, offer a level of stability non-dividend payers don’t.  They’ve shown an ability to generate sufficient cash to pay those dividends over extended periods.  Cash is fact.  Profit is theory.  Focusing on facts (cash) reduces my risk while being side-tracked by non-facts (profit expectation) increases it.

Consistent delivery of dividends makes estimating future cash flows more reliable which reduces risk.  A company with an unpredictable history of cash generation and market volatility makes accurate forecasting problematic – my guess is as good as the next guy’s.  In such cases, it’s easy to fall victim to trend-itis.  The technical trading crowd takes full advantage.

Trends:
Trends are either up or down; they’re binary.  If I bet the up and it goes down, I lose.  What’s more, a change in trend can be considerable.  The lack of directional predictability and potentially large scale shifts in magnitude increase risk by making it difficult to project where my investments are headed.  It’s akin to driving down the interstate as fast as you can while blindfolded.  It may be exciting, but you increase the probability of going in the ditch – or worse.

Long-term Averages:
Averages logo
Long-term averages can pay off.
Long-term averages, however, smooth the ride.  The binary outcome becomes a range offering greater probability of success.  In other words, results generally revert to the average over time and typically don’t stray far from it.  This fact reduces the likelihood of a large miss in my forward estimation mitigating my risk to a degree. 

Long-run dividend histories offer a readily definable average and target range.  The same can’t be said for momentum investing that simply bets the over / under.  The latter becomes a function of buy low / sell high - market timing.  The timers enjoy limited success.

Looking forward through a stable, predictable lens, improves my investment vision.  The better the vision, the lower the risk.  That’s why I prefer to bet the averages with Dividend Champions and not the trends.

The thoughts and opinions expressed here are those of the author, who is not a financial professional.  Opinions expressed here should not be considered investment advice.  They are presented for discussion and entertainment purposes only.  For specific investment advice or assistance, please contact a registered investment advisor, licensed broker, or other financial professional.  

Monday, October 22, 2018

Investment Diversification: Is more better?


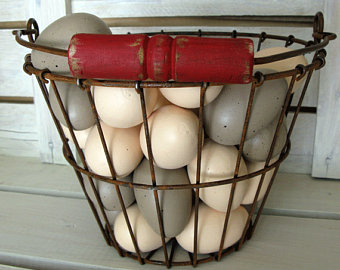
Investment egg basket.
Investment Egg Basket
As mentioned in the post 5.5. Reasons Dividend Stocks Beat Index Mutual Funds, the prospect of buying a huge basket of stocks in an index fund doesn’t really provide better risk mitigation than could be had with a compact basket of 20-30 stocks – probably even fewer.  In this case, the risk being discussed is that your invested funds disappear courtesy of an unforeseen business disaster on the part of the company in which you invested.  The general premise of this piece is laid out below.

Scenario #1:  Your money is invested entirely in Company A which has a 10% chance of going out of business for various reasons.  This means you have a 10% chance of losing your entire nest egg.

Scenario #2: You split your investment portfolio evenly across Companies A and B.  Both firms are in unrelated segments like transportation and health care in which case the probability of either entity going under is independent of the other doing likewise. 

The probability of Company A going out of business remains 10% as in the first scenario.  The probability of Company B going belly up is also 10%.  What now is the probability of completely losing your shirt because both companies tank at the same time?  The companies are in unrelated industries in which case the probability of one going out of business is independent of the probability of the other going out of business.  The probability of two unrelated events happening simultaneously is determined by multiplying the probably of A times the probability of B: 

Probability A (10% ) x Probability B (10%) or .10 x .10 = .01 or 1%.

By spreading your investment pool from one company to two companies in divergent industries you’ve reduced your risk of losing everything from 10% to 1%.

Scenario #3: You think to yourself that if investing in 2 companies reduces risk, then investing in 3 companies has to be better still.  (It is, to a very small degree.)  Therefore you spread your wealth across three companies (A, B, C) each with an independent probability of going out of business of 10% because they are all in unrelated industries.  Now the risk of losing your life savings is calculated by multiplying the risk of A x B x C shown here:

Probability A (10%) x Probability B (10%) x Probability C (10%) or .10 x .10 x .10 = .001 or one-tenth of one percent.

By spreading your investment pool from two companies to three you’ve reduced your risk by nine-tenths of one percent.  The risk reduction generated isn’t large but the added workload in monitoring the third firm is, relatively speaking.

Carry this math across 15 or 20 firms and you’ll see the risk reduction becomes excruciatingly small while the management workload increases greatly in proportion.   

The math means that an index fund with hundreds or thousands of companies held within it produces no meaningful risk below that of a small, selective portfolio of quality companies as far as I’m concerned.  It does, however, generate a lot of extra work OR management fees for the index mutual fund.  Brokers and money managers like that fact.  It works to their advantage when millions of investors aren’t paying attention.

Investopedia does a nice job summarizing investment risk.  Systemic or market risk which can’t be diversified away (think inflation) and unsystemic risk which is germane to a specific company.   The unsystemic risk is what diversification is designed to mitigate.  As you can see from the examples above, the law of diminishing returns is prominent rendering moot the advantage of holding hundreds or thousands of firms in a single fund and paying a fee for the privilege of doing so.

Andrew Carnegie once said “The way to become rich is to put all your eggs into one basked and then watch that basket.”  I’m not comfortable with that advice nor am I comfortable with the current wisdom endorsing investors to put a little money into every basket and watching none of it.  Let the pros watch it for you – for a fee.  With a little work and a few tools, it’s possible you can cultivate good ground somewhere in between.  You can concentrate on solid, dividend paying companies in a diversified portfolio of 20 to 30 holdings, maybe fewer, avoid annual fees, and succeed.  It’s worth investigating, right?

The thoughts and opinions expressed here are those of the author, who is not a financial professional, and therefore should not be considered as investment advice.  This information is presented for education and entertainment purposes only.  For specific investment advice or assistance, please contact a registered investment advisor, licensed broker, or other financial professional.